
Cherry Financing and CareCredit are the two third-party payment options patients bring up most when a treatment plan costs more than they want to pay in one visit, and picking the wrong one can add unnecessary interest to work that's already an investment. This guide breaks down how each one actually works, where each wins, and which fits your situation before you sign anything in 2026.
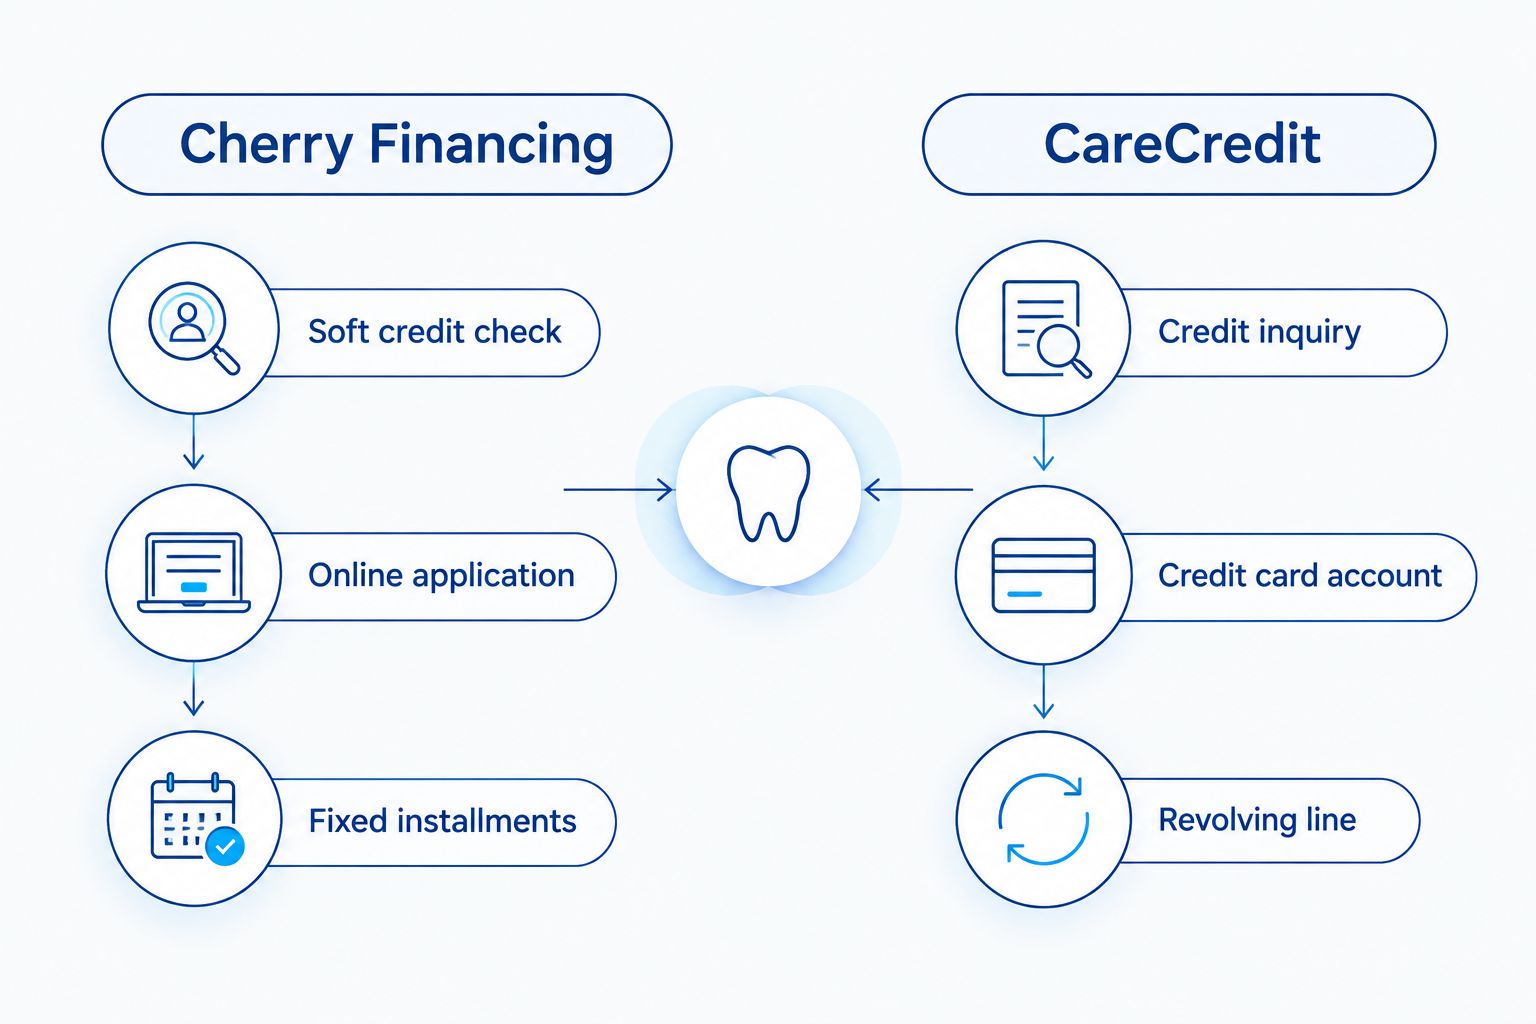
- Cherry Financing uses a soft credit check and fixed monthly installments; CareCredit works like a revolving credit card.
- Cherry Financing suits patients who want predictable, capped payments on one treatment plan.
- CareCredit suits patients who already hold the card and want to reuse it across future visits.
- Both require full repayment inside the promotional window to avoid deferred interest on the entire balance.
- Neither is offered directly by Dental Arts of Atlantis in 2026 — both are third-party lenders you apply to separately.
Why This Matters
A crown, an implant, or a full Invisalign case rarely arrives on a schedule that matches your checking account. Dental Arts of Atlantis fields questions about payment options almost daily from Palm Beach County patients weighing a treatment plan against a household budget in 2026.
The American Dental Association recommends a checkup every six months, but the big-ticket work — root canals, implants, full-arch cases — shows up without warning and rarely waits for open enrollment or a bonus check. That's where Cherry Financing and CareCredit come in: both let a patient split a treatment cost into payments instead of one lump sum, but the mechanics behind each are different enough to matter.
Neither company is affiliated with Dental Arts of Atlantis. Both are independent lenders — you apply directly with them, and the practice simply accepts the payment once you're approved.
At a Glance: Cherry Financing vs CareCredit
| Dimension | Cherry Financing | CareCredit |
|---|---|---|
| Best for | First-time applicants who want a simple installment plan | Patients who already use the card at other healthcare providers |
| Credit check type | Soft check for pre-qualification | Standard credit inquiry |
| Approval speed | Fast, online, same visit | Fast, online, same visit |
| Payment structure | Fixed installment loan | Revolving credit card |
| Provider network | Growing, healthcare-focused | Broad, long-established across medical and dental offices |
| Fee transparency | Terms disclosed at application | Terms disclosed at application |
| Mobile account tools | App-based tracking | App-based tracking |
| Best for large treatment plans | Keeps one loan, one payment | Can be reused across multiple procedures over time |
Best For: Cherry Financing Suits Patients Who Want One Simple Plan
Cherry Financing is built around a single treatment plan getting a single, fixed monthly payment — no card to manage, no revolving balance to track. If you want to finance one dental case and be done with it, that structure is the easier one to live with.
CareCredit is built differently: it's a credit line you can draw against repeatedly, which is the better fit if you expect ongoing dental, vision, or other healthcare costs beyond this one visit.
Credit Check: Cherry Financing Uses a Softer Screening Process
Cherry Financing typically starts with a soft credit check for pre-qualification, which means checking your eligibility doesn't ding your credit score before you commit. That matters for patients who are rate-shopping or unsure whether they'll qualify at all.
CareCredit runs a standard credit inquiry as part of its application, which is the same process used for most retail credit cards. Neither approach is wrong — but Cherry Financing's soft-check step gives you a lower-risk way to see where you stand first.
Approval Speed: Both Platforms Move Fast
Cherry Financing and CareCredit both process applications online and typically return a decision the same day you apply, often within minutes. Neither one requires a follow-up appointment just to find out if you're approved.
This is a genuine tie — speed isn't the variable that should decide which one you pick. Structure and how you plan to use it should.
Payment Structure: One Works Like a Loan, the Other Like a Card
Cherry Financing functions as an installment loan: you borrow a set amount for the treatment plan and pay it back in equal chunks until it's done. CareCredit functions as a credit card: you're issued a credit line, you draw against it for the visit, and the balance behaves like any other card balance until you pay it off.
If predictable, capped payments matter more to you than flexibility, Cherry Financing's structure is the better match. If you want a reusable line you can tap again for a cleaning, a filling, or a future procedure without reapplying, CareCredit's card model does that better.
Provider Network: CareCredit Has the Broader Reach (by a Lot)
CareCredit has been in the healthcare financing space far longer than Cherry Financing and is accepted at a wider range of medical, dental, vision, and veterinary providers nationwide. If you split care across several providers, CareCredit's established network is the stronger fit.
Cherry Financing's network skews more toward dental and elective healthcare specifically, which is narrower but still covers general, cosmetic, and implant dentistry cases without issue.
Fee Transparency: Read the Terms on Both Before You Sign
Both companies disclose their financing terms at the point of application, and both structure their promotional offers around a repayment window tied to deferred interest. This is a tie in terms of transparency — the terms are there in writing for both — but it's on you to actually read them before you commit.
“If the balance isn’t paid off before the promotional window closes, deferred interest applies retroactively to the entire original balance, not just what’s left.”
That single mechanic is the most common regret patients report with any deferred-interest financing product, Cherry Financing and CareCredit included. Set a calendar reminder for your payoff date, not just your monthly due date.
Mobile Account Management: Both Offer App-Based Tracking
Cherry Financing and CareCredit both offer online account dashboards and mobile access for checking your balance, due dates, and payment history. Another tie — the day-to-day experience of managing either account looks similar.
Large Treatment Plans: Cherry Financing Keeps Bigger Cases Simpler to Track
For a single large case — a full-arch implant plan, a full-mouth reconstruction, a comprehensive Invisalign case — Cherry Financing's one-loan, one-payment structure is easier to track than a revolving balance that can grow if you keep charging to it. Patients weighing financing dental implants without insurance often find a fixed installment plan easier to budget against than an open-ended credit line.
CareCredit still handles large cases fine — it just requires more discipline not to keep drawing on the card for smaller add-ons along the way.
How the Cost Structure Works
Neither company publishes identical terms for every applicant — your rate and repayment window depend on your credit profile and the amount financed, so specific figures aren't something to guess at here. What's worth understanding is the tradeoff between the two models.
Cherry Financing's installment structure gives you predictability: one loan amount, one end date, payments that don't change. CareCredit's revolving structure gives you flexibility: a credit line you can reuse, pay down, and draw against again without a new application each time. Predictability suits a single, known treatment cost. Flexibility suits ongoing or unpredictable care needs.
Whichever you choose, the same rule applies: know your payoff date before the promotional period ends, because deferred interest on either product applies to the full original balance if you miss it, not just the remainder.
Get Your Treatment Cost Estimate
See the full cost of your treatment plan before deciding how to finance it.
Final Verdict
Choose Cherry Financing if: you're financing one defined treatment plan, you want a soft credit check before committing, and you'd rather have a fixed payment that doesn't change until the loan is paid off. A patient budgeting for a single implant or an Invisalign case in 2026 is the clearest match for this model.
Choose CareCredit if: you already use the card at another provider, you want a credit line you can reuse across multiple visits over time, and you're comfortable managing a revolving balance responsibly. A patient juggling dental work alongside other ongoing healthcare costs is the clearer match here.
| Dimension | Winner |
|---|---|
| Best for first-time applicants | Cherry Financing |
| Softer credit check | Cherry Financing |
| Approval speed | Tie |
| Payment predictability | Cherry Financing |
| Provider network size | CareCredit |
| Fee transparency | Tie |
| Mobile account tools | Tie |
| Large treatment plans | Cherry Financing |
FAQ
Is Cherry Financing better than CareCredit for dental work?
Cherry Financing works better for a single treatment plan with a fixed monthly payment; CareCredit works better if you want a reusable credit line across multiple healthcare visits. Neither is universally better in 2026 — it depends on how you plan to use it.
Does Cherry Financing require a hard credit check?
Cherry Financing typically starts with a soft credit check for pre-qualification, which doesn’t affect your credit score. A hard inquiry may follow only once you formally accept an offer.
Can I use CareCredit for cosmetic dentistry?
CareCredit is commonly used for both medically necessary and elective dental work, including cosmetic procedures. Acceptance depends on the specific provider, so confirm with the practice before applying.
What happens if I don’t pay off a deferred-interest plan on time?
Missing the payoff date on either Cherry Financing or CareCredit’s promotional plans typically triggers interest applied retroactively to the full original balance, not just the remaining amount. Mark your payoff date, not just your due date.
Which is better for a first-time dental patient with limited credit history?
Cherry Financing’s soft credit check makes it easier to see your eligibility without a hard inquiry first, which is generally friendlier for patients with limited credit history. CareCredit’s approval depends more heavily on standard credit criteria.
Can I use both Cherry Financing and CareCredit at the same practice?
Many dental practices accept multiple third-party financing options, but availability varies by provider. Ask directly which options a specific practice accepts before you apply.
Does Dental Arts of Atlantis offer its own payment plans?
Dental Arts of Atlantis does not extend its own in-house payment plans. Patients arrange financing directly through third-party companies like Cherry Financing or CareCredit, and the practice accepts payment once approved.
What’s the difference between a payment plan and a credit card for dental costs?
A payment plan like Cherry Financing’s installment model gives you a fixed loan amount and a set end date. A credit card model like CareCredit gives you a reusable credit line that can be drawn on repeatedly, with a balance that behaves like any other card.
One Last Thing
The detail that trips up the most patients isn't which company they pick — it's forgetting the payoff date on a deferred-interest plan. Whether it's Cherry Financing's installment loan or CareCredit's revolving line, missing that date turns a 0%-style promotional period into interest charged on the entire original balance. Set the reminder the day you sign, not the week before it's due.
Related Guides
- Best dental financing plan for a family budget
- Check what your dental insurance covers before you book
- Best dental membership plan for uninsured families